
EMT Targets Faster Economic Growth, Harmonises Government’s Key Economic Assumptions
The Federal Government has taken steps to strengthen economic planning and coordination with the establishment of an inter-agency committee to harmonise key macroeconomic assumptions used in budgeting and economic management.
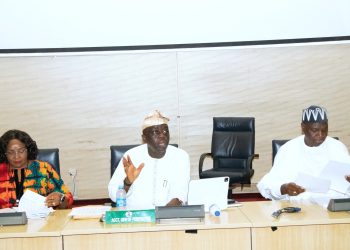
The decision was reached on Monday, September 7, 2026, at a meeting of the Economic Management Team (EMT) in Abuja, chaired as part of the Federal Government’s efforts to improve economic coordination and accelerate growth across key sectors.
The new committee will harmonise projections on crude oil prices and production, exchange rates, inflation and non-oil revenues used by fiscal and monetary authorities.
According to the EMT, the move became necessary following a joint budget retreat and technical validation workshop which identified inconsistent assumptions among government agencies as one of the factors contributing to budget under-performance.
The committee is also expected to address inconsistencies in the reporting of key economic indicators to government, external stakeholders and the public.
Economy Records Stronger Growth
The EMT noted that Nigeria’s real Gross Domestic Product (GDP) grew by 4.43 per cent year-on-year in the second quarter of 2026, representing the strongest quarterly performance since the third quarter of 2024.
The meeting also noted that external reserves had risen above $54 billion in early September, the highest level in nearly 18 years, according to Central Bank of Nigeria data.
The naira has also strengthened to its firmest level in about two years, trading in the N1,300s to the US dollar in early September.
The Team further welcomed the decision by FTSE Russell to reclassify Nigeria from “Unclassified” to “Frontier Market” status, effective September 21, 2026.
The reclassification is expected to improve the visibility of Nigerian equities among international investors.
The EMT was also briefed that public debt remains below 40 per cent of GDP, while Nigeria’s sovereign credit outlook by Moody’s has improved from stable to positive.
The Team noted that Nigeria’s economy, measured in purchasing-power-parity terms, is valued at more than $2.2 trillion, highlighting the country’s potential to achieve a $1 trillion nominal GDP by 2030.
Stronger Economic Data Coordination
The EMT approved a revised Terms of Reference which expands its responsibilities to include macroeconomic performance reviews, stronger fiscal and monetary coordination, monitoring of Renewed Hope Agenda priorities and periodic assessment of the Federal Government’s financing needs.
The Team also adopted a monthly meeting schedule, with at least two strategic sector reviews to be conducted at each sitting.
To improve the reliability and consistency of official economic statistics, the Ministry of Finance was designated as the coordinating custodian for national economic data, while relevant government agencies will remain responsible for providing data within their respective areas of responsibility.
FG Targets Agriculture Growth
The EMT also reviewed measures aimed at increasing agriculture’s contribution to the government’s ambition of building a $1 trillion economy by 2030.
The strategy includes reducing post-harvest losses, expanding agricultural processing and mechanisation, improving export compliance and ensuring timely release of capital ahead of planting seasons.
The Team further reviewed plans to recapitalise the Bank of Agriculture and establish a new credit window for smallholder farmers.
Government is also targeting an increase in agriculture’s share of private-sector credit to 10 per cent by 2030.
Nigeria Prepares for CANEX 2026, IATF 2027
The EMT reviewed preparations for Nigeria to host the Creative Africa Nexus (CANEX) in November 2026 and the Intra-African Trade Fair (IATF) in November 2027, both in Lagos.
The events are expected to attract exhibitors, international buyers and, in the case of IATF, African heads of state, with significant trade and investment deals projected.
The Ministry of Finance was tasked with coordinating funding and customs facilitation, in collaboration with the Ministry of Industry, Trade and Investment.
The two ministries are also expected to develop a consolidated action plan with clearly assigned responsibilities to relevant ministers.
The Minister of Finance and Coordinating Minister of the Economy said the decisions were aimed at ensuring greater consistency between government projections and actual economic outcomes.
“Today’s decisions tighten the link between the numbers we plan with and the actual outturns. A single, harmonised set of assumptions across the fiscal and monetary authorities means fewer surprises in the budget and more credible planning for investors and all Nigerians.”